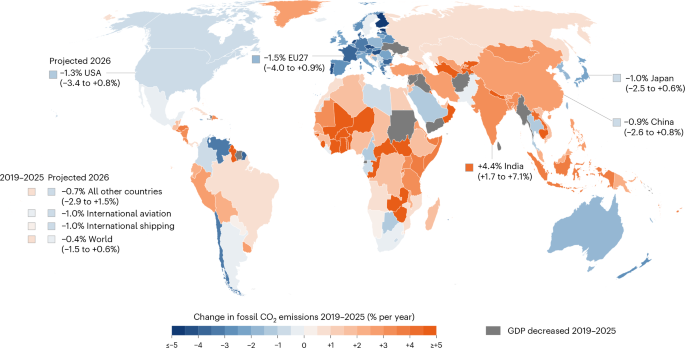
Efforts to tackle climate change are taking place amidst a background of profound changes, with wars leading to upheavals in global energy markets, a shift in government priorities towards defence, high capital costs, barriers to trade, the boom in artificial intelligence (AI) and new data centres and also a retrenchment in some places from climate targets. The global transition to cleaner energy continues despite this 1 , with the rapid expansion of renewable energy 2 , batteries for storage 1 and electrified transport 3 , supported by self-reinforcing feedback loops between falling costs and deployment 4 , 5 .
The acceleration in the energy transition has contributed to widespread decreases in fossil CO 2 emissions 6 , 7 , 8 . With data up to 2025 now available 9 , 59 countries emitted less in 2025 than before the COVID-19 pandemic in 2019, while their economies grew (Fig. 1 ), 51% more than during 2004–2010 (39 countries; Extended Data Fig. 1 ). Although a decrease in emissions over such a short 6-year period does not necessarily mean that country emissions have peaked, the growing number of countries illustrate the geographical expansion of the energy transition across Europe, North America, parts of South America, Japan, South Korea, Australia and several middle-income countries such as South Africa, Thailand, Colombia and Mexico. Even in countries where total emissions have increased over the 2019–2025 period, growth in emissions has slowed in all regions including in China, India and other emerging economies 10 , and certain sectors appear to have arrived at or be near their peak, such as the road transport sector in China. Notably, CO 2 emissions in China—the largest contributor to global emissions (32% in 2025)—are projected to decrease 0.9% in 2026 (Fig. 1 ) and to be comparable to their 2023 levels.
Despite the expansion of the energy transition 1 , 2 , 3 , global fossil CO 2 emissions continued to rise in 2025 (1.2%) 10 , but they are projected to decrease by 0.4% in 2026 (Fig. 1 and Methods ). The 2026 decrease is driven by 1.9% and 0.3% decreases in emissions from oil and gas, respectively, which are partly offset by a 0.6% increase in emissions from coal (Fig. 2 and Extended Data Fig. 2 ). Here we quantify the effect of the recent and likely near-term trends in the energy transition and other drivers on global fossil CO 2 emissions to assess how they might influence the timing of global peak emissions.
We estimated the effects of electric vehicles (EVs) and solar and wind power renewable energy on global fossil CO 2 emissions as the emissions avoided at the country level, assuming that in their absence the same service would have been supplied by fossil fuels. All other drivers are represented by global gross domestic product (GDP) as a proxy for underlying demand growth and by a counterfactual CO 2 intensity of GDP, defined as actual plus avoided emissions divided by GDP, calculated separately for coal, oil and gas. The contributions of EVs, solar and wind power, GDP and counterfactual intensity sum exactly to the actual change in fossil CO 2 emissions ( Methods ).
We estimated the effect of EVs (including battery, plug-in hybrid and hybrid vehicles) by assuming that EV sales replace internal combustion vehicles and calculating the emissions avoided from 2010 to 2026 on the basis of available statistics 11 ( Methods ). The effect is growing rapidly but remains small because the vehicle stock takes time to turn over, with only 10% of the car fleet electrified in 2025 (6% excluding non-plug-in hybrids) and far less for vans and heavy-duty vehicles. Emissions avoided by EVs rose from 0.03 GtCO 2 in 2019 to 0.19 GtCO 2 in 2025 and a projected 0.24 GtCO 2 in 2026 (Extended Data Fig. 3 ). Despite their low numbers, other EVs account for 30% of the emissions avoided by EVs, because each replaces a vehicle with much higher fuel use. Avoided emissions in China (97 MtCO 2 ), the USA (30 MtCO 2 ) and the European Union (EU27; 27 MtCO 2 ) account for 82% of the 2025 total. Emissions avoided were large enough to slow the growth of global oil emissions, which rose by 0.38 GtCO 2 , compared with 0.53 GtCO 2 in the counterfactual without EVs. However, the 0.05 GtCO 2 increase in avoided emissions in 2026 above 2025 accounts for only 20% of the projected decrease in oil emissions, with most of the oil decrease probably reflecting the higher oil prices and supply constraints driven by conflicts in Iran and elsewhere ( Methods ).
We estimated the effect of renewable energy for solar and wind only, assuming that they displace coal and gas in electricity generation and using available statistics from Ember 1 ( Methods ). Emissions avoided by renewable energy rose from 0.28 GtCO 2 in 2010 to 4.1 GtCO 2 in 2025 and a projected 4.6 GtCO 2 in 2026 (Extended Data Fig. 3 ). China accounts for half the 2025 total (2.1 GtCO 2 ), followed by the USA and EU27 (0.5 GtCO 2 each) and India (0.3 GtCO 2 ). In 2025, renewable energy accounted for 95% of the total avoided emissions (renewable energy plus EVs). three-quarters of the estimated avoided emissions come from displaced coal and one-quarter from displaced gas. The projected increase in coal emissions in 2026 (0.6%; 0.09 GtCO 2 ) occurs despite the continued growth in renewable energy, which, all else being equal would reduce coal emissions by 0.38 GtCO 2 and probably reflects underlying demand drivers. For gas, the effect of renewable energy (0.11 GtCO 2 ) more than accounts for the projected decrease in emissions (0.3%; 0.03 GtCO 2 ).
Many factors besides avoided emissions influence the growth of CO 2 emissions, including energy demand primarily associated with development 4 , but also new demand sources (such as the production of batteries, the electricity used by EVs and new data centres), energy efficiency and changes in the fossil fuel mix (for example, from coal to gas) and in the wider energy mix (for example, year-to-year variability in hydro and nuclear output). We estimated the combined influence of these other drivers by comparing the growth rate of CO 2 emissions with that of GDP, following a Kaya Identity approach 12 ( Methods and Extended Data Fig. 4 ). Without the emissions avoided by EVs and renewable energy, we estimate that global CO 2 emissions would have grown by 1.9% per year on average during 2019–2025 driven by economic growth and changes in the CO 2 intensity of the economy. This is more than double their actual growth of 0.8% per year. The AI-driven expansion of data centres plays only a minor role in the growing demand in 2025 (0.03 GtCO 2 , which is 2% of the demand-related emissions; Methods ).
We then project the contributions of each driver between 2025 and 2028. Emissions avoided by EVs and renewable energy are projected by fuel type under present- and accelerated-deployment scenarios, both using available statistics for the year 2026 ( Methods ). For years 2027 and 2028, the present-deployment scenario holds annual EV sales and solar and wind capacity additions at their 2026 levels, while the accelerated-deployment scenario projects EV sales shares and solar and wind generation shares using logistic curves fitted to data from 2019 to 2026 (Extended Data Tables 1 and 2 ). For the demand-related drivers, we extrapolate the counterfactual CO 2 intensity of GDP for each fuel and multiply it by projected GDP (International Monetary Fund (IMF) 13 ). Projected emissions for each fuel are then the product of GDP and counterfactual fuel-specific intensity, minus the projected avoided emissions (Fig. 2 ). The envelope of projections reflects the plausible ranges of GDP growth, the intensity trend and the deployment of EVs and solar and wind power, but it does not account for short-term fluctuations such as the expected recovery from the 2026 energy shock, which would come on top of these trends.
The near-term projection to 2028 shows that energy transition drivers are not yet strong enough to overcome the anticipated emissions from demand growth (Fig. 2 ). Between 2025 and 2028, GDP and intensity trends alone would increase emissions by 2.59 GtCO 2 , of which EVs and solar and wind power offset 1.64 GtCO 2 (63%) in the present-deployment scenario and 2.04 (79%) in the accelerated-deployment scenario. For year 2026 alone, EVs and renewable energy offset two-thirds (69%) of the demand-related growth (Extended Data Figs. 5 and 6 ). For coal, in the accelerated case, the rapid growth of solar and wind power offsets the strong underlying growth from demand and projected emissions fall slightly by 2028. For gas, solar and wind power offset half the underlying increase, so that emissions continue to grow in both scenarios when all drivers are combined. For oil, EVs offset more than half the underlying (pre-Iran) increase from demand growth, but only because this increase is itself small. The effect of EVs is now small relative to total oil emissions because of the slow turnover of the vehicle fleet and the concentration of EV adoption in passenger cars, but it is expected to grow over time. Those trends are consistent with the International Energy Agency (IEA) World Energy Outlook 2025 14 (Stated Policies Scenario), in which coal demand peaks and declines before 2030, gas demand keeps growing into the 2030s and oil demand flattens by the end of this decade. The envelope of scenarios shows that decreasing emissions could occur already from 2026, but this would require an unlikely combination of low GDP growth, low CO 2 intensity of GDP, accelerated clean technology deployment and the high range of assumptions used in this calculation (Extended Data Tables 3 and 4 ).
The underlying drivers projected here take into account trends that are mostly before the Iran war, which has led to increases in oil prices and supply constraints that probably explain the large decrease in oil emissions in 2026. The associated energy shock masks the underlying structural drivers of emissions. This conflict has had widespread consequences, from governments cutting fuel taxes to increases in supply elsewhere (particularly US crude and products) to shifts to EVs and renewables as governments attempt to reduce dependence on volatile international energy markets. Some of these responses push emissions up and others down, adding to the strong opposing drivers that mask the timing of peak emissions.
Despite the very strong opposite drivers, this analysis suggests that the projected decrease in global fossil CO 2 emissions in 2026 is not a sign that emissions have peaked from the transition to cleaner energy, but is probably a short-term response to higher oil prices and supply constraints following the Iran conflict. Nevertheless, the emissions avoided by clean technologies are substantial, and their rapid annual growth is estimated to offset around 64–79% of the increase in emissions from all other drivers combined in the near term. If further acceleration of clean technology deployment can be supported through time, a sustained peak and decline in global CO 2 emissions could be a few years away.
Historical emissions and recent country trends
Historical emissions estimates and the 2026 projections are from the 2026 update of the Global Carbon Budget 9 , which use methods described in the 2025 update 10 . Total emissions include emissions from coal, oil, gas, cement (including cement carbonation), gas flaring and other smaller sources 15 . Only UN countries are counted in the country list in the text. Country counts are made for the periods 2004–2010 and 2019–2025 which are representative of the long-term trend (Extended Data Fig. 1 ) and exclude the COVID-19 and 2008–2009 global financial crisis years in their start and end points.
Conceptual framework and limitations of near-term drivers of emissions approach
The avoided emissions approach is a simplified counterfactual assumption that does not demonstrate causation. Particularly for short-time frames, fluctuations from weather causing changes in heating or cooling demand and influencing the availability of hydro and nuclear energy and global market or economic shocks will also influence emissions and may hide the underlying drivers. However, there is strong evidence that the secular trends in solar, wind and EVs do lead to lower emissions. The avoided emissions approach simply quantifies these drivers, with an indicative uncertainty around parameter choices and plausible assumptions near-term deployment.
Avoided emissions from EVs
The effect of EV substitution was estimated by assuming new EVs replace internal combustion vehicles, reducing the associated tailpipe emissions. Estimates are based on available statistics for the period 2010–2026 and projected following two scenarios for years 2027 and 2028. For passenger cars (including light trucks where these are reported in car sales, for example in the USA), the stock of battery EVs (BEVs), plug-in hybrids (PHEVs) and hybrids (HEVs) was estimated for 52 countries from cumulative monthly new registrations based on the collected vehicle registration database 11 , accounting for scrappage with a mean lifetime of 15 years. The total car stock was from Eurostat for Europe, national statistics for 12 countries and IEA estimates 3 elsewhere. Road transport CO 2 emissions by country were from the IEA-EDGAR CO 2 database 16 , 17 . The attributable to cars ( 20–75%) was estimated from national GHG inventories or the literature. Each BEVs, PHEV and HEV was assumed to avoid 100%, 30% and 20%, respectively, of the average emissions for passenger cars in each country. Avoided emissions from other vehicles were estimated for the largest emitters (China, India, EU27 and USA). Electric stocks by class (buses, heavy trucks, light commercial vehicles and 2/3-wheelers) were from national statistics where available, and otherwise built from annual sales or registrations or industry and non-governmental organization publications. CO 2 emissions per combustion vehicle were from national inventories where available, or otherwise estimated from annual distance and fuel use. Electric 2/3-wheelers that mostly replace non-motorized transport were assumed to replace only part of a combustion vehicle. Avoided emissions were split between oil and natural gas according to the fuel mix of the vehicles replaced. For the year 2026, sales for each vehicle type for available months (January–September for most countries) were compared with sales over the same months in 2025 and the ratio was applied to 2025 full-year sales. For the 2027–2028 projection, we use two scenarios. The present-deployment scenario uses 2026 sales values through 2028. The accelerated scenario places the BEV on a logistic curve fitted to 2019–2026 shares, with PHEV and HEV shares following their 2024–2026 linear trend (Extended Data Table 1 ). For other vehicles, 2025 electric sales were held constant in both scenarios. Sensitivity tests to model assumptions based on plausible values 18 , 19 , 20 suggest an indicative uncertainty range of −19% to +25% for the avoided emissions growth between 2025 and 2028 (combining individual sensitivity tests in quadrature; Extended Data Table 3 ).
Avoided emissions from solar and wind renewable energy
The effect of renewable energy was estimated for solar and wind only, assuming that they displace coal- and gas-fired electricity generation. Annual solar, wind, coal and gas generation for 220 countries and territories was taken from Ember yearly electricity data 1 . Solar and wind generation was assumed to displace coal and gas in proportion to their shares of combined coal and gas generation in that year of each country and the displaced generation for each fuel was multiplied by its emissions factor (0.95 kgCO 2 kWh −1 and 0.45 kgCO 2 kWh −1 for coal and gas, respectively). For 2026, solar and wind generation for available months (January–September for most countries) was used to estimate the full year as for the EVs. For the 2027–2028 projection, the present-deployment scenario holds the annual additions of solar and wind generation for each country at their 2025–2026 increment (with negative increments set to zero). The accelerated-deployment scenario placed the solar and wind of electricity generation on a logistic curve fitted to 2019–2026 shares (Extended Data Table 2 ). Displaced generation was split between coal and gas in proportion to the 2026 coal and gas generation of each country. Sensitivity tests to model assumptions based on plausible values suggest an indicative uncertainty range of ±7% for the avoided emissions growth between 2025 and 2028 (Extended Data Table 4 ).
We focus on solar and wind because they account for nearly all the recent growth in low-carbon electricity. Hydro and nuclear generation have been broadly flat globally and mainly affect year-to-year variability, whereas bioenergy grew only slowly.
Counterfactual emissions from demand-related drivers
All other drivers are represented by world GDP and by a counterfactual CO 2 intensity of GDP for each fuel. Counterfactual emissions were calculated for 2010–2025 as actual emissions (by fuel type) plus avoided emissions and counterfactual intensity as counterfactual emissions divided by GDP. Thus for the historical period, the actual emissions ( E FOS ; by fuel type) decompose into: E FOS = ( E FOS + E avoided )/GDP × GDP − E avoided , where ( E FOS + E avoided )/GDP × GDP is the demand linked to GDP and E avoided is the calculated avoided emissions described above. GDP was taken as world real GDP at purchasing power parity from the IMF World Economic Outlook (October 2026) 13 . For years 2026–2028, scenarios combine uncertainty from three factors: projected GDP growth, the rate of decline in counterfactual intensity and the projected avoided emissions. The central estimate uses IMF GDP projection (October 2026), the central counterfactual intensity averaged over 2015–2025 and projected avoided emissions. The low and high estimates combine the lowest and highest GDP growth each year among the IMF (October 2026), World Bank (June 2026) and Organisation for Economic Co-operation and Development (September 2026) forecasts, with the steepest and flattest intensity trends among alternative fit periods (2010–2025, 2015–2025 and 2019–2025 and 2021–2025). The low- and high-fit periods were selected on the combined coal, oil and gas emissions and applied to each fuel, to preserve substitution between fuels within each period. These low and high estimates were then combined with the present and accelerated deployment of avoided emissions scenarios, including their uncertainty. The envelope of projections combines the extremes of each range and is therefore not a probabilistic range.
Emissions from the growth in data centres
We estimate that the growth in electricity use by data centres, driven largely by AI, added approximately 0.03 GtCO 2 in 2025. This is the 2025 increase in their consumption ( 70 TWh, +17%; IEA 21 ) multiplied by the average carbon intensity of the electricity they use given the present fuel mix (0.43 tCO 2 MWh −1 ). That is 2% of the demand-related increase in 2025 (+1.39 GtCO 2 ) calculated here.
Drivers of projected 2026 emissions
The projected decline in 2026 emissions does not align with the combined drivers because it is influenced by additional short-term factors. The global decline is predominantly due to a 1.9% decline in oil emissions. This oil decline coincides with petrol and diesel pump prices that were 10–50% higher in the USA, China and EU27 depending on the fuel and the period, compared with 2025 prices, following the Iran war. A mean rise of 20% would correspond to a short-run elasticity of 0.1 for oil use (percentage change in oil demand per percentage change in price) which is consistent with the published literature 22 . Other factors can also contribute, in particular supply constraints due to the limitations in the Hormuz strait passage and conflicts elsewhere, and the availability of EVs and transport alternatives.
Generative AI (Claude, Anthropic: model Opus 5.5, October 2026) was used under the continuous supervision of the lead author (C.L.Q.) to write the Python code for the clean technology substitution models, to find and download input data from the publicly available sources cited in the paper and to write the code that produced the analysis and figures. Each step was planned and approved. The code was run using Python by the lead author. Assumptions, intermediate results and final outputs were checked by the author and results were validated against independent published estimates. An independent technical and scientific verification was conducted using GPT-6 to ensure the assumptions described in this paper were coded adequately and justified. The use of each dataset was checked against its licence and terms of use. No figures are AI-generated images. Claude was also used to help clarify the text after it was drafted. The authors take full responsibility for the content of this paper.
The full story
This article is one source in a clustered incident — the cluster page carries the summary, timeline and every other outlet covering it.
